Photo: Sceenshot USDEBTCLOCK.ORG
(Editors Note – This is a follow up to Buzzocles’ Comprehensive Analysis of Commodity Prices and the Economy. Link below JT)
Date: October 11, 2026
Prefix: The Commodity Conflation Fallacy
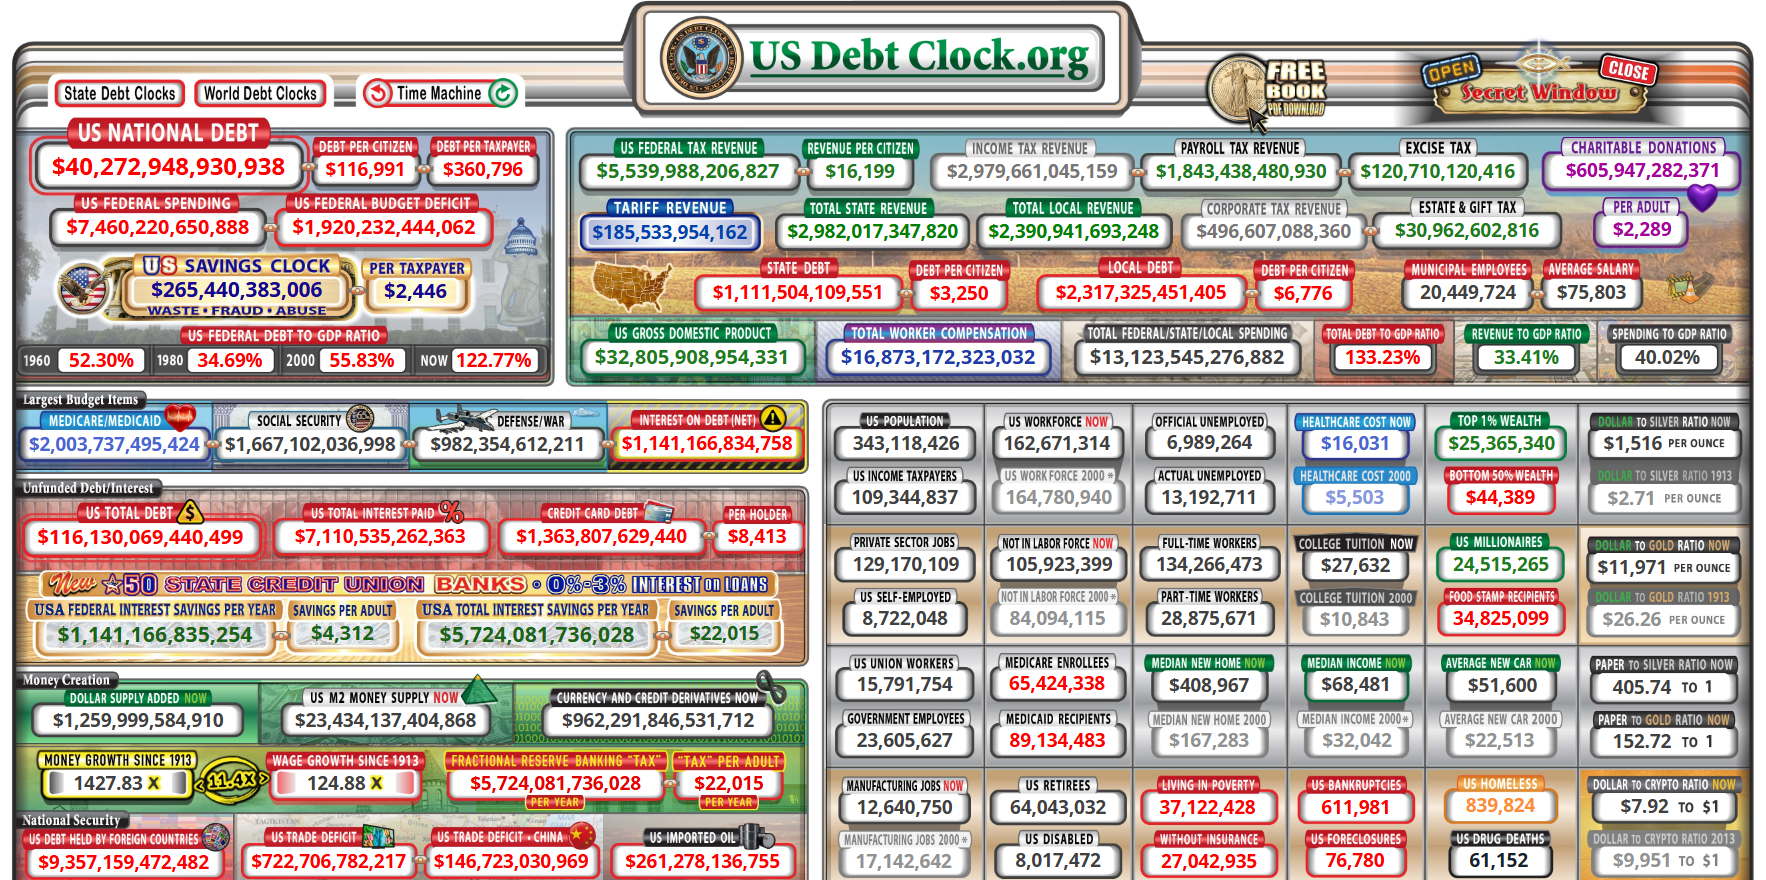
True market pricing is never the product of an isolated metric. To view silver purely through the lens of COMEX drawdowns is a fundamental analytical error. Commodities operate within a synergistic matrix of geopolitical friction, monetary debasement, and physical constraints. The continuing depletion of the Strategic Petroleum Reserve (SPR) will eventually lead to the demise of this quasi artificial source of oil. The subsequent price hikes in diesel, gasoline, and petroleum-derived products will stimulate cost-push inflation in an economy already suffocating under a $40+ trillion in sovereign debt. Capital may flee to preserve value, seeking perhaps to transition to silver, but in this case, it will collide with an inelastic industrial floor that cannot substitute its inputs. The resulting price rise will not be caused by one variable, but by the simultaneous confluence of many – the peril of this reality explicitly verified this week by the continued carnage in the Strait of Hormuz, and renewed Houthi attacks on Saudi oil and civil infrastructure.
Last week’s audit addressed the concept of the interest-to-revenue insolvency threshold. While the precise level of this limit is debatable, and arguably at least somewhat related to the specific culture in question, the general proposition is that when net interest obligations breach a level of around 30% interest payments-to-revenue, traditional monetary and administrative policy levers break down entirely. The state cannot use legislative force or punitive extraction to solve its concomitant systemic fiscal decay. Attempts to force compliance, whether through higher taxes or asset appropriation, risk triggering immediate capital flight and a contraction of the productive base at best, and at worst, rebellion. This structural resistance is deeply woven into the decentralized socio-historical foundation of the American population, where cultural precedents historically reject aggressive state extraction and coercive mandates.
While this was more thoroughly addressed in last week’s audit, we postulated the 30% level without quantifying our exact proximity to it or mapping the velocity of our approach. The preceding week’s physical supply disruptions and evolving macro pressures have pulled that abstract timeline directly into the immediate horizon. The decline in U.S. sovereign creditworthiness is increasingly locked into a non-linear feedback loop given the petroleum supply crisis. We have previously discussed the “Straits Taylor Rule,” and its implications for limits to Fed rate increases. Similarly, the march toward the 30% interest/revenue limit exposes the limits of state ability to impose standard policy measures.
When the U.S. Treasury attempts to auction new paper to pay the interest on its old debt under these conditions, the market pushes back. Lenders demand an explicit risk premium to absorb the supply, forcing auction clearing yields higher. Every basis point increase triggered by these shifting auction dynamics feeds directly back into the federal debt-service requirement, compounding the deficit, weighing on lender confidence, and structurally locking in the absolute mandate for nominal debt monetization. This feedback loop will lead to an inexorable and single recourse, the debasement of the dollar in order to avoid national insolvency. We will return to this topic momentarily. But first we address the basic metrics previous identified as relevant to the price of silver over the next 11 months or so.
Macro Indicator Matrix Update
| Macro Variable | Current Magnitude (Oct 11, 2026) | Velocity (Weekly Rate of Change) | Model Impact |
| Silver Spot Price | $61.28 / troy oz | Consolidating at Support | Locked at historical support limits following a volatile consolidation from its January peak. |
| COMEX Registered Float | 99.3M – 101.4M ounces | Multi-Year Vault Drain | Reclassification dynamics fail to hide a systemic above-ground vault depletion of 762.1M oz since 2021. |
| U.S. Strategic Petroleum Reserve (SPR) | 282.98Mb | – 790,000 barrels | Continuing to approach the ~ 250M limit. |
| Physical Oil (“Dated Brent”) | $149 / Barrel | + 42.8% Premium over Paper | Extreme physical spot premium driven by total maritime denial, bypassing paper derivative market. |
| U.S. Sovereign Debt | $40.38 Trillion | +$120 Billion | Maturing debt refinancing squeeze. Net interest obligations consume 21.17% of actual FY2026 revenues. |
| Geopolitical Choke Point | Closure | Expanded Kinetic Strikes | Severe infrastructure and tanker hits this week confirm Western military efforts have been operationally bypassed. |
Discussion
Why the SPR Buffer is Becoming Irrelevant
The primary administrative mechanism utilized to suppress petroleum prices continues to approach its technical and legal boundaries. Dropping beneath the 252.4-million-barrel statutory threshold will suspend executive authority to order routine, non-emergency price-relief releases. Furthermore, repeated emergency draw downs risk damage to the cavern infrastructure. Low internal cavern pressures are reducing maximum extraction capabilities down to a restricted 1.0 to 1.4 million barrels per day, meaning the reserve cannot physically scale to replace the Gulf deficit.
Strait of Hormuz Operational Disruption & The Freight Penalty
The temporary pipeline bypass strategies noted in prior audits have been rendered entirely ineffective. A severe escalation of successful kinetic strikes—with devastating hits targeting both commercial tankers and maritime energy infrastructure over the preceding days—confirms that combatants have bypassed the defensive envelope established by the West. The resulting effective closure disrupts the pre-conflict rate of 20 million barrels of oil per day. Commercial maritime fleets have abandoned the Red Sea and Persian Gulf routes, opting for long-haul transits around the Cape of Good Hope. This rerouting structurally links higher transit timelines and expanded maritime insurance premiums directly into the domestic wholesale index. See physical oil price in table above.
The Limits of Coercion & Mandatory Debt Monetization – Returning to Our Opening Discussion
When a state reaches the mathematical ceiling outlined in our stress-test scenarios, the standard levers of governance dissolve. In a domestic setting defined by deep-seated historical foundations—rooted in the collective narrative of decentralized resistance to punitive tax extraction—direct asset expropriation or coercive enforcement will completely fail to manufacture economic productivity or generate real tax revenue.
The table below depicts our estimates of the Interest/Revenue ratio beginning with 2026 baseline data ($5.400 Trillion in total revenue collected against $1.143 Trillion in net interest on public debt), extrapolating with the ongoing credit and energy squeeze:
| Fiscal Year | Case A: Current Steady State (Interest +11% / Rev +3%) | Case B: Auction/Fed Squeeze (Interest +16% / Rev +3%) | Case C: Stagflationary Shock (Interest +16% / Rev -2% Recession) |
| FY 2026 (Actual) | 21.17% (Baseline) | 21.17% (Baseline) | 21.17% (Baseline) |
| FY 2027 | 22.81% | 23.84% | 25.06% |
| FY 2028 | 24.59% | 26.85% | 29.66% |
| FY 2029 | 26.50% | 30.24% (Breached) | 35.11% (Breached) |
| FY 2030 | 28.56% | 34.06% | 41.56% |
| FY 2031 | 30.77% (Breached) | 38.36% | 49.19% |
| Terminal Wall | 5 Years (FY 2031) | 3 Years (FY 2029) | 3 Years (FY 2029) |
Because physical force cannot clear a mined shipping corridor or compel an industrial mining desk to extract metals at a structural loss under punishing input costs, the state’s enforcement levers remain economically impotent. Under intense regulatory or coercive pressure, the productive base naturally executes a tactical withdrawal—capital flees the jurisdiction, and real economic output drops toward zero as the risk-reward ratio of trading tangible labor for unbacked paper currency completely evaporates. This pulls our timeline out of Case A and accelerates it directly into the non-linear realities of Case B and C, leaving the state with a singular path: nominal monetization of the debt, cementing systemic currency debasement – with all its implications for the price of finite, physical silver assets.
This Week’s Conclusion: The Analyst Blind Spot and the 30% Countdown
The ongoing extreme premium paid for physical spot commodities shows that paper derivative contracts are losing their ability to dictate real-world asset pricing. Yet, it remains highly bemusing to observe silver bound within the $60 to $62 range. Mainstream analysts are mesmerized, completely consumed by hyper-fixtion on minor 48-hour macro adjustments like technical wedge breakouts and temporary breathers in the U.S. Dollar Index. This myopic focus represents the exact fulfillment of The Commodity Conflation Fallacy: the market treats silver as a speculative playground while remaining blind to the structural debt gears turning right beneath its feet.
This is not fear-mongering; the 21.17% interest-to-revenue ratio is an actual, historically verified danger zone. It is not just an arbitrary milestone on the way to 30%; it marks a critical structural inflection point where a sovereign math trap snaps shut. Sovereign debt experts and fiscal watchdogs like the Committee for a Responsible Federal Budget (CRFB) explicitly warn that when a nation’s net interest outlays consume around 19% to 22% of total federal revenue, the state loses its ability to absorb economic shocks.
As mapped out in the preceding table, the U.S. sovereign debt apparatus has already crossed into this zone, and the velocity toward the terminal 30% limit is accelerating with every shifting auction dynamic. Short-term desks are celebrating temporary pauses in yields, missing the reality that while nominal tax receipts grew 3% to $5.400 Trillion due to inflation, the corporate tax base faces severe future contraction as industrial margins compress under sustained cost-push energy inputs. Once the market finally realizes that the state is entirely trapped—incapable of raising rates to lower debt costs without aggressively pulling the FY 2029 absolute debt-monetization timeline forward—the panic out of financialized instruments and into finite, physical assets will trigger an explosive revaluation. The only question remains: when will this realization occur? Until then, as discussed in previous ‘Sunday Night Audits,’ forced, price-inelastic industrial buyers will continue to drain an already exhausted vault system, while short-term capital sleeps on a mathematical certainty.