By Billy Ray Valentine CBNC Business News
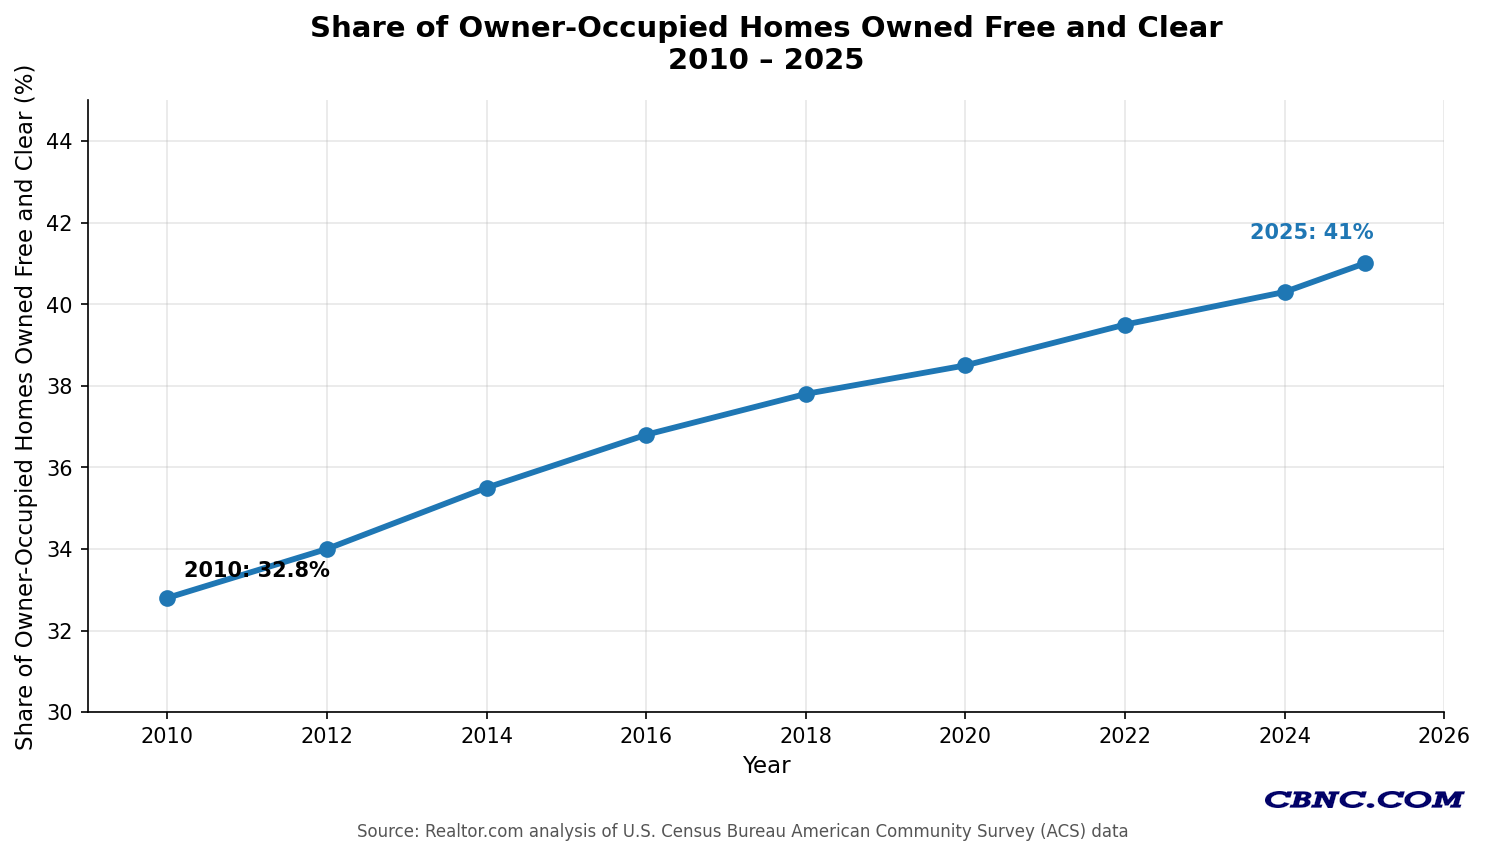
Forty-one percent. That is the share of American homeowners who own the roof over their head free and clear. No bank. No servicer. No monthly bill from a lender. They paid it off. They carried their own water, and nobody in Washington ever threw them a parade.
Now the other number. 3.93 million. That is how many homeowners aged 75 and older are still paying on a mortgage. In 2010 it was 1.79 million. That is up 119%. Grandpa is supposed to be burning the mortgage papers. Instead he is mailing a check to the servicer at 80. This is America, and somebody ought to ask how we got here.
The numbers come from a Realtor.com analysis of the Census Bureau’s 2025 American Community Survey, published Monday by economist Jiayi Xu. The share of owner-occupied homes owned outright rose from 32.8% in 2010 to 41% in 2025. The share carrying a mortgage fell from 67.2% to 59%. That is the good news. The country got a little more paid-for.
THE MORAL HAZARD
Here is the part nobody in the Beltway wants to talk about. Look at who owes. The District of Columbia has the highest share of homes with a mortgage in the whole country, 73.5%. The Washington metro area tops the 50 biggest metros at 73.6%. The town that runs the national credit card also runs the biggest tab on its own houses.
Now look at who paid off. West Virginia has the lowest mortgage share in America, 43.4%. Pittsburgh, Buffalo and Oklahoma City sit near the top for homes owned outright. Grand Rapids, Michigan, leads the big metros for seniors with no mortgage at 79.2%. Pittsburgh is at 78.4%. Buffalo, 75.6%. Kansas City, 75.5%. Milwaukee, 75.4%. Those are working towns. Those are people who bought what they could afford and paid it down.
That is the moral hazard in one map. For fifteen years, Washington taught the country that debt is free. Rates near zero. Cash-out refinancing. Borrow against the house to pay for the kitchen, the truck, the grandkid’s tuition. The people who listened are the ones still paying at 75. The people who ignored the sales pitch are the ones sleeping easy now.
And the loans got bigger. Citing the Federal Reserve’s Survey of Consumer Finances, the report puts median home-secured debt for households 75 and older at $101,000 in 2025. In 2010 it was $77,720. That is about 30% more debt on people who are supposed to be living on fixed incomes.
WHO PAYS
The senior with a $101,000 balance pays first. Every dollar of that payment comes out of a Social Security check or a pension that does not grow as fast as prices have. Wholesale prices rose 6.5% in a year through October. The mortgage payment does not care.
The young family pays second. Xu’s report says owners with low-rate loans may hold onto their homes longer. With rates back above 7%, the lock-in effect is likely to tighten the market again. The oldest baby boomers turned 80 this year. Their homes are supposed to come back to the market and give a young couple a shot. A senior still carrying a mortgage, or locked into a cheap one, has every reason to stay put. Fewer listings. Higher prices. The kid working two jobs pays for that.
The free-and-clear owner, meanwhile, is the one American Washington cannot squeeze through the mortgage. Xu writes that owners who own outright “are likely indifferent to changes in borrowing costs.” They can sell when they want. They can buy the next place in cash. Rate shock? Not their problem. They earned that.
THE BOTTOM LINE
Here is the lesson. Paying off your house is still the most conservative, most American financial move a family can make. It beats every promise Washington ever made about cheap money. The 41% who did it are the backbone of this market.
So defend them. Stop punishing savers with inflation that eats their cash. Stop rewarding the borrower with every new program and every new bailout. And stop telling 75-year-olds that a cash-out refinance is a retirement plan.
The people in West Virginia figured this out. The people in Washington, D.C., still have not. That tells you who should be giving the advice.
Sources:
realtor.com/research/mortgage-status-acs-2026
realtor.com/news/trends/mapped-states-most-mortgage-free-homeowners-west-virginia-acs-2026
finance.yahoo.com/real-estate/article/a-growing-share-of-homeowners-dont-have-a-mortgage-at-all-110000858.html
realtywire.com/owners-75-mortgage-free-and-clear-realtor
realtor.com/news/trends/housing-week-ahead-construction-insights-rental-trends-and-pending-sales
cnbc.com/2026/11/16/treasury-yields-bonds-inflation.html