By Billy Ray Valentine CBNC Business News
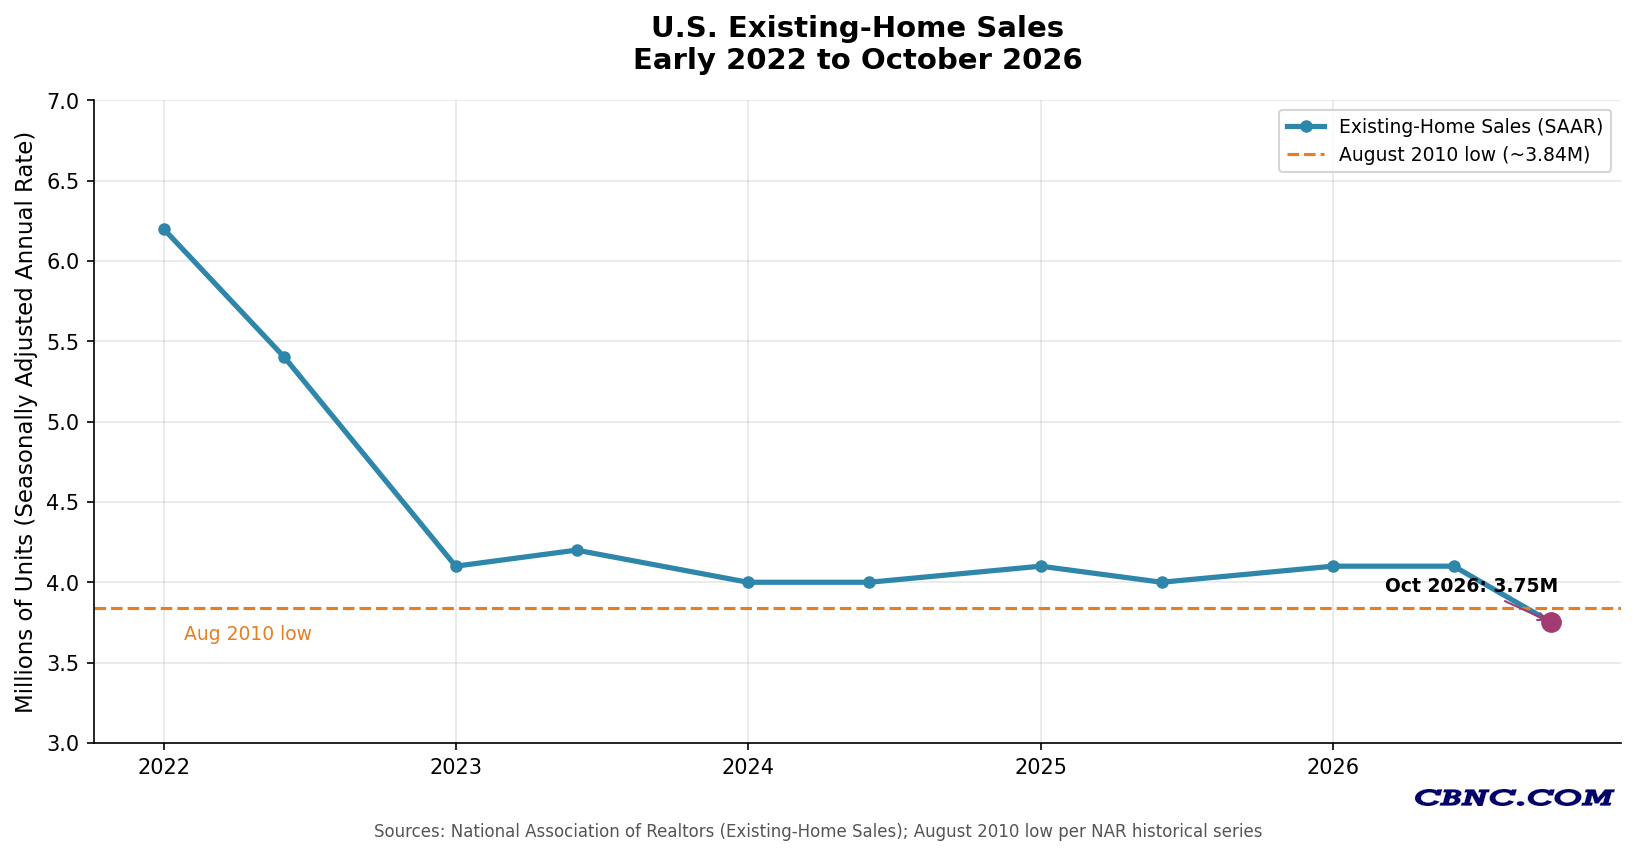
3.75 million. That is the pace Americans are buying homes right now. Lowest since August 2010. Lowest since the wreckage of the last housing crash. And look who is still at the table. Not the kid who saved. The guy with cash.
First-time buyers fell to 29% of sales in October, the National Association of Realtors said Thursday. A year ago they were 32%. Historically they run about 40%. Investors and second-home buyers jumped to 20%, up from 16%. Cash deals rose to 29%. This is America. The young family that carried its own water for five years is standing outside the house. The buyer with the briefcase walks right in.
The Tape
Existing-home sales fell 5.5% in one month and 8.8% from a year ago, per NAR. Economists expected around 3.8 million to 3.85 million. They got 3.75 million. Sales dropped year over year in every region. Sales fell even in the $1 million-and-up tier, the corner of the market that was supposed to be bulletproof.
And still the price will not break. The median home sold for $416,700, up 0.4% from a year ago. That is the 40th straight month of year-over-year gains, and the highest October median on record. Inventory rose to 1.59 million homes, a seven-year high, per Realtor.com. Supply climbed to 5.1 months, the most in 11 years. Homes sat a median 35 days.
Buyers are gone. Sellers are not budging. That is a frozen market, and frozen markets do not freeze evenly.
The Moral Hazard
Here is what nobody in Washington wants to say out loud. The people locked out today are paying for the people who got bailed in yesterday.
Washington and the Fed flooded the country with cheap money during the pandemic. Owners grabbed loans at rock-bottom rates and sat tight. Federal Reserve economists admitted it in their own paper: rising rates in 2022 “significantly increased moving costs for homeowners with low fixed-rate mortgages, leading to a sharp drop in mobility.”
So the houses never came to market. Prices never reset. The average home has appreciated by $146,000 over the past seven years, NAR says. That is wealth handed to whoever owned first. Lawrence Yun, NAR’s chief economist, says owners are “largely in a comfortable financial position due to sizable housing wealth accumulation.”
Comfortable for them. Not for the electrician renting a two-bedroom and putting, say, $500 a month aside. He did everything right. He paid his bills. He saved. And he watched the down payment he needed run away from him faster than he could chase it.
Meanwhile the cash buyer and the investor do not need a loan. They do not care what the bank charges. Their share of the market goes up every time the working buyer gets squeezed out. That is the moral hazard. Easy money made the first owners rich, and tight money now hands the leftovers to whoever already has the most.
Who Pays
Frank Cassidy, President Trump’s former FHA commissioner, told The Epoch Times: “Americans want to buy homes, but high mortgage rates and affordability challenges are keeping an entire generation of first-time buyers on the sideline.”
He is right. And he added: “We don’t need another study or another promise. We need action.”
Chris Rupkey, chief economist at FWDBONDS, put it plainer to CNBC: “It’s dark out there with no homebuyers anywhere to be found.”
It is not only buyers who pay. The real estate agent paid on commission pays. The moving company pays. The local furniture store pays. The title office and the home inspector pay. When 3.75 million homes change hands instead of the more than 6 million pace of early 2022, every one of those small businesses on Main Street takes the cut.
The Bottom Line
Do not let anyone tell you this is a “healthy cooling.” Healthy is a 30-year-old with a job buying a starter home. What we have is a market that pays the people who already own and charges the people who are trying to start.
The fix is not another federal program. It is not another subsidy that drives prices higher. It is sound money, a Washington that stops spending like a drunk, and local governments that let builders build. Until then, the folks who carry their own water keep standing at the curb while the cash rolls past.
Sources
https://www.nar.realtor/newsroom/existing-home-sales-decreased-5-5-percent-october-nar-report
https://www.theepochtimes.com/business/existing-home-sales-fall-to-lowest-level-since-august-2010-nar-6124299
https://www.realtor.com/news/trends/existing-home-sales-data-nar-october-2026/
https://www.inman.com/2026/11/12/existing-home-sales-sink-to-a-16-year-low-as-mortgage-rates-bite/
https://www.cnbc.com/2026/11/12/us-treasurys-bonds-yields.html
https://www.editusa.com/business/existing-home-sales-october-2026-lowest-since-2010-mortgage-rates