Taxpayers and investors are mostly on the hook this time, not banks.
By Wolf Richter for WOLF STREET.
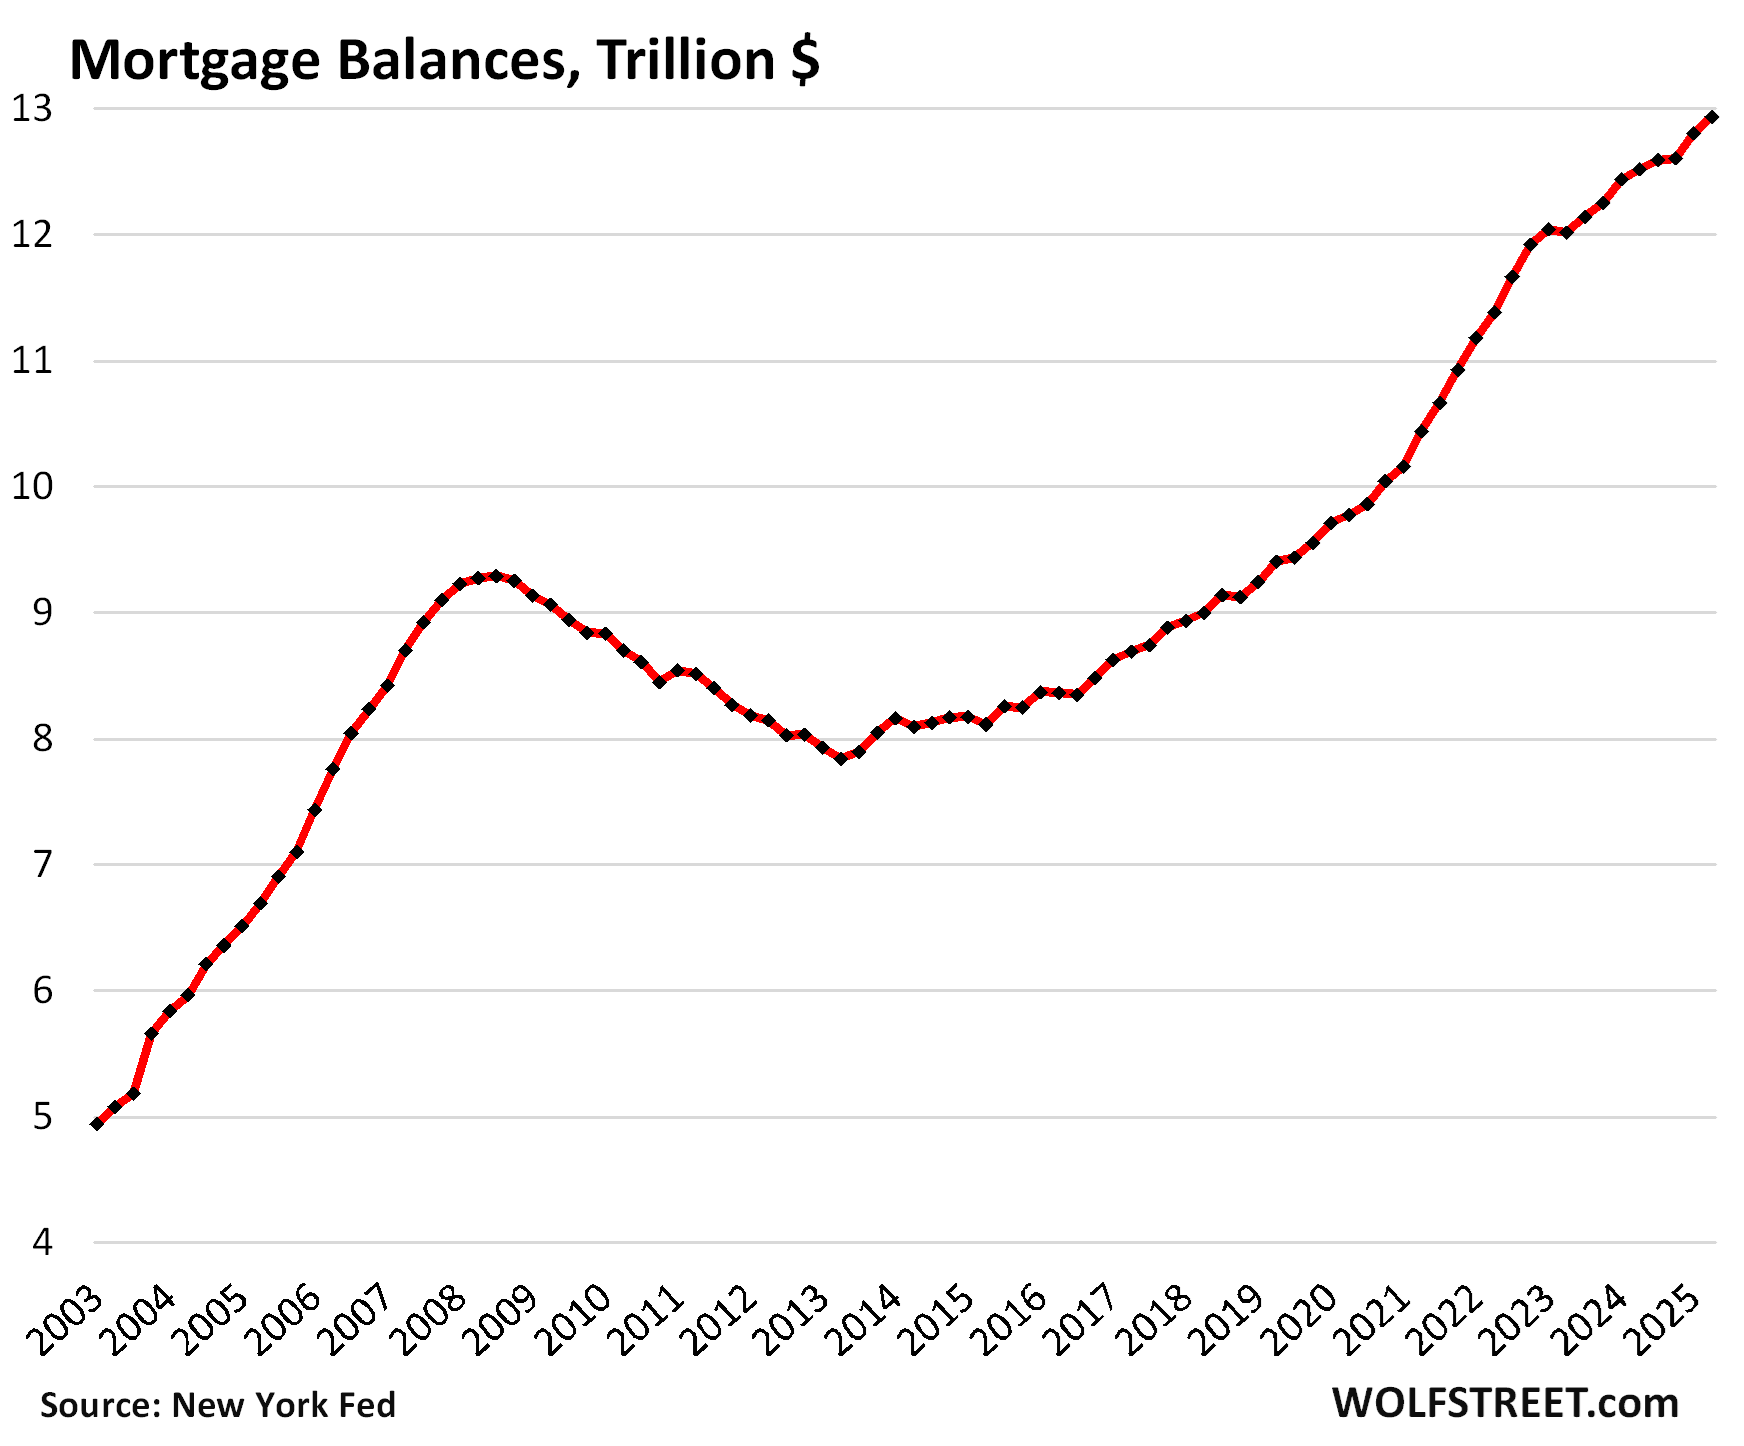
Mortgage balances rose by $131 billion (+1.0%) in Q2 from Q1, and by $416 billion (+3.3%) year-over-year, to $12.9 trillion, according to the Household Debt and Credit Report from the New York Fed, based on Equifax credit report data.
Back in 2021 and 2022, the year-over-year increases were in the 8-10% range. Since then, demand for existing homes has plunged despite spiking supply, while demand for new houses has been soft despite a supply glut.
In general, mortgage balances rise when homeowners sell their home with a partially or fully paid-off mortgage, while the buyer gets a new mortgage for most of the purchase price. Mortgage balances also rise with cash-out refinancing of existing mortgages. And they rise when homebuilders and condo developers sell a new home…