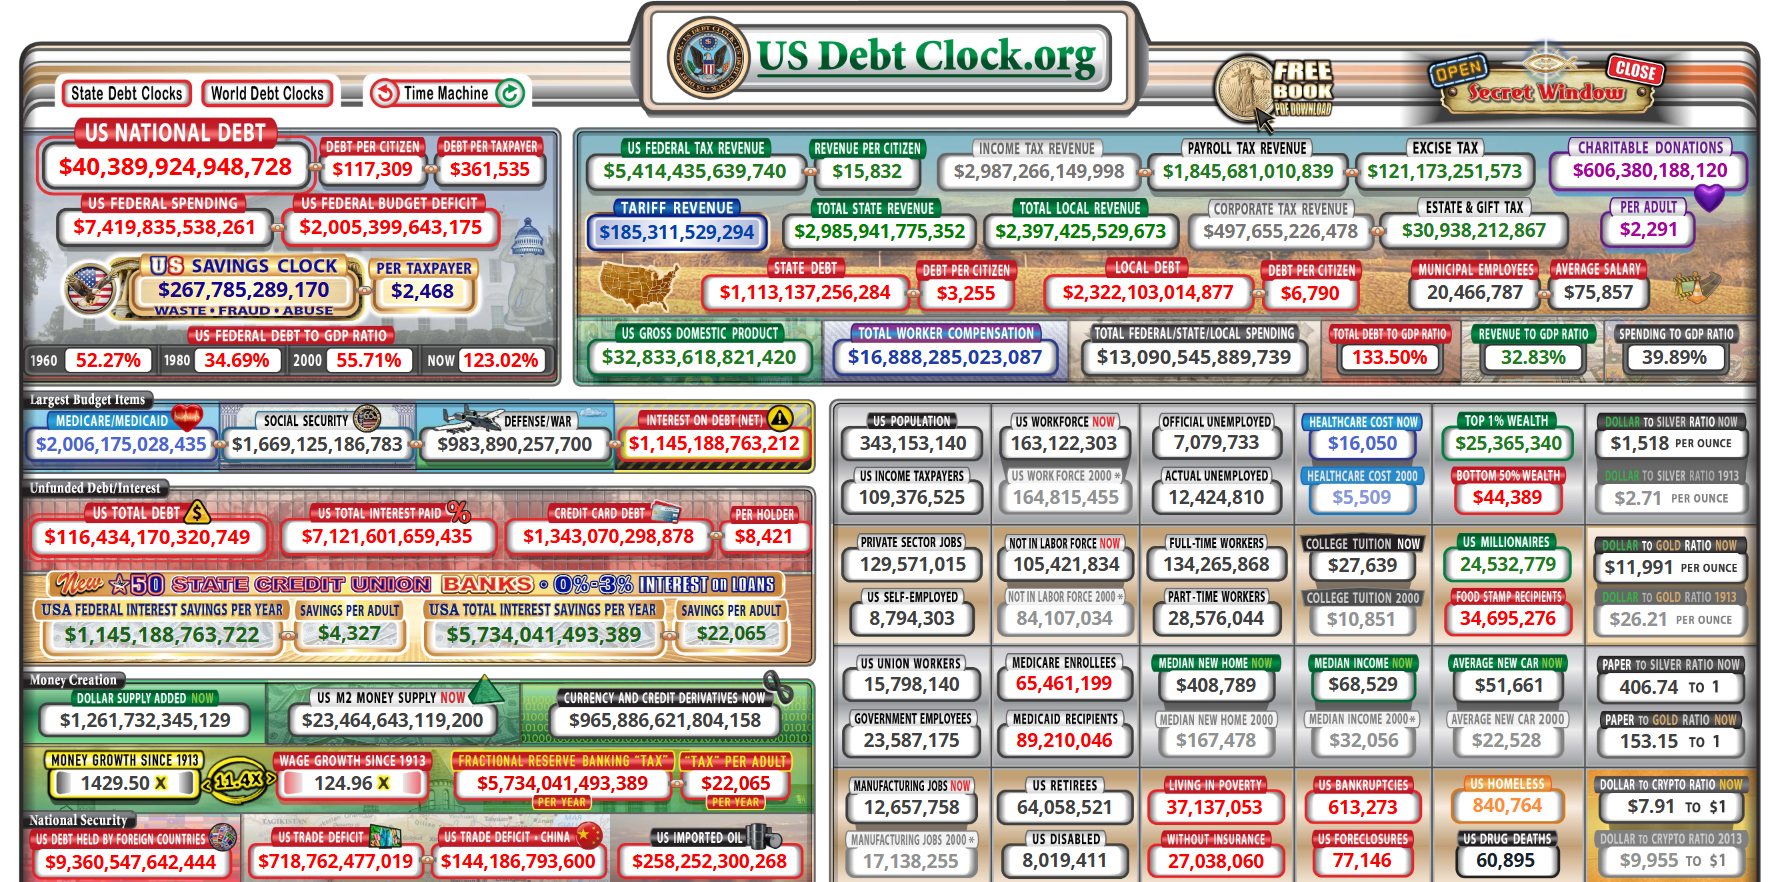
Screenshot of USDebtClock.org
The Sunday Night Audit
(Editor’s Note – This is a follow up to Buzzocles’ Comprehensive Analysis of Commodity Prices and the Economy. Link below – JT)
Date: October 19, 2026
Prefix: The Commodity Conflation Fallacy
True market pricing is never the product of an isolated metric. To view silver purely through the lens of COMEX draw downs is a fundamental analytical error. Commodities operate within a synergistic matrix of geopolitical friction, monetary debasement, and physical constraints. The depletion of the Strategic Petroleum Reserve (SPR) will, alongside concurrent factors, stimulate cost-push inflation in an economy already suffocating under a $40+ trillion sovereign debt wall. It is a wall because at this level the Federal Reserve has little recourse to its traditional monetary tools. Capital may flee to preserve value, seeking perhaps to transition to silver, but in this case it will collide with an inelastic industrial floor that cannot substitute its inputs. The resulting price rise will not be caused by one variable, but by the simultaneous confluence of many.
This week’s audit explores a distinct operational divergence between institutional research signaling and exchange depository architecture, focusing specifically on J.P. Morgan’s published commodity outlook and warehouse metrics. While public-facing reporting from their research division projects lower silver prices based on industrial demand “thrifting,” exchange warehouse registries indicate that institutional client and house accounts have concurrently expanded their physical bullion holdings within proprietary vaults [J.P. Morgan]. We will examine the physical parameters of the 5 mg per watt solar paste engineering floor to evaluate how these competing commercial forces shape market sentiment and physical float liquidity.
Concurrently, the global logistical landscape reflects mounting pressures as maritime transit reallocations alter supply line cost baselines. Expanded shipping timelines, elevated war risk premiums, and the degradation of regional pipeline bypass options continue to separate physical spot indices from synthetic futures markets. To establish a standardized, mathematical gauge for these compounding geopolitical frictions, transit traffic drops, and freight penalties, this audit formally implements and monitors the Gulf Energy Disruption Index (GEDI).
Updated Macro Indicator Matrix (October 19, 2026)
| Macro Variable | Current Magnitude (Oct 19, 2026) | Velocity (Weekly Rate of Change) | Model Impact |
| Silver Spot Price | $57.89 / troy oz | -$3.39 (Weekly change) | Consolidated price action continues near established technical support zones, with physical coins and retail bullion maintaining standard single-digit dealer premiums. |
| COMEX Registered Float | 99.3M – 101.4M ounces | Stable Low Volume | Deliverable inventory remains bounded near multi-year lows, reflecting a persistent net depletion of above-ground exchange floats since 2021. |
| U.S. Strategic Petroleum Reserve (SPR) | 282.98M barrels | Flatlined (0 weekly draw) | Weekly draw rates have stabilized, indicating that administrative price-suppression mechanisms have reached an infrastructure floor. |
| National Average Retail Diesel | $6.53 / Gallon | Sustained Flat at Highs | High commercial transport costs continue. |
| Physical Oil (“Dated Brent”) | $117.00 / Barrel | -$32.00 (Two-week correction) | Physical spot crude has corrected downward but retains a structural premium over paper futures contracts due to Red Sea re-routing penalties. |
| U.S. Sovereign Debt | $40.38 Trillion | +$120 Billion (Two-week expansion) | Total public debt expanded over the multi-week window; net debt service outlays consume 21.17% of actual fiscal year revenues. |
| Geopolitical Choke Point (Strait of Hormuz) | Severe Transit Drop | Ongoing Shipping Friction | Daily traffic remains heavily constrained against an 85-ship baseline. While transponder-verified visible public traffic has cratered into the single digits (4–10 ships/day), We conservatively retain a 31-ship ceiling to account for un-tracked dark convoy operations shepherded by Western naval escorts. Prohibitive insurance parameters keep standard commercial traffic paralyzed. |
| Gulf Energy Disruption Index (GEDI) | 42.19 (Critical Print) | +13.39 (Multi-week acceleration) | The index confirms that supply-chain overhead—driven by a 30x insurance multiplier and a 58.6% drop in crossings—is structurally locked at catastrophic levels. |
Section 1: Institutional Structural Discrepancies & The 5 mg Thrifting Floor
The core structural anomaly in the current silver landscape lies in the explicit divergence between institutional market projections and underlying exchange registry behavior. On October 13, 2026, J.P. Morgan Global Research published a comprehensive commodity update outlining a cautious near-term outlook for silver [J.P. Morgan]. The report argued that a sharp 30% reduction in solar-application industrial demand was structurally locked in due to aggressive “thrifting” measures across global solar photovoltaic manufacturing lines, capping their late-2026 price target at a conservative $70 per ounce [J.P. Morgan].
However, this public thesis relies on a glaring macro modeling error. A 30% reduction in solar application paste consumption does not mathematically translate into a 30% drop in aggregate global silver demand unless solar manufacturing accounts for 100% of the market. By failing to weigh this application-specific reduction against the broader industrial landscape—including expanding automotive electronics, premium semiconductors, and defensive investment allocations—the institutional model presents an incomplete demand layout. When this premature demand-destruction narrative is juxtaposed against a global mining infrastructure facing its sixth consecutive structural deficit, the underlying market balances remain highly tight.
Furthermore, a comparative audit of exchange depository logs reveals an entirely different operational posture within vault registries. Regardless of standard market-making, client clearing, or internal delta-hedging operations, audited exchange registries show that J.P. Morgan client and house accounts have quietly consolidated an unrivaled physical position, amassing an estimated 195 million to 210 million ounces of physical bullion within their proprietary depository networks. This physical concentration represents roughly 25% of annual global mine production, establishing a profound inventory buffer precisely while public-facing research models emphasize a diminishing industrial requirement [J.P. Morgan].
This analytical gap is further illuminated when evaluating the hard engineering limits of solar paste economization. Mainstream models assume that industrial thrifting is a linear process that can shrink silver usage indefinitely via fine-line screen printing and zero-busbar architecture. However, empirical studies from the University of New South Wales (UNSW) and Fraunhofer ISE confirm that this engineering vector has encountered an unyielding physical brick wall at approximately 5 mg per watt.
Attempting to drive silver metal paste loadings below this 5 mg threshold introduces a severe, non-linear risk cascade:
Electrical Resistance: Thinner silver grid lines create systemic micro-breaks and inadequate wafer metallization, causing series electrical resistance to skyrocket, which bottlenecks energy output and induces localized cell overheating.
Delamination Vulnerabilities: Minimizing the paste mass compromises the structural integrity of the solar panel’s soldered contacts. Under standard daily thermal expansion and contraction cycles, these weakened contacts risk delaminating entirely.
Because alternative metallization technologies—such as copper substitution—face unresolved oxidation, cross-contamination, and rapid degradation limits in dominant n-type TOPCon solar architectures, commercial manufacturing desks cannot thrift beyond the 5 mg floor without exposing themselves to catastrophic, 25-year product liability claims. Consequently, industrial procurement remains highly inelastic. J.P. Morgan’s warehouse accumulation pattern suggests an operational recognition of this structural floor: by utilizing a pessimistic paper narrative to anchor public sentiment and compress spot futures pricing, institutional house and client desks have successfully accumulated physical inventory within a highly favorable pricing window before real-world factory desks drain the remaining unencumbered exchange float [J.P. Morgan].
Section 2: Implementing the Gulf Energy Disruption Index (GEDI)
To move past qualitative rhetoric regarding geopolitical tension, this audit formally implements the Gulf Energy Disruption Index (GEDI) as a standardized mathematical tool to quantify supply-chain friction. Standard macroeconomic models consistently miscalculate commodity pricing because they treat geopolitical stress as an abstract sentiment variable. In reality, modern asymmetric conflict manifests as a highly measurable logistical penalty that directly impacts the All-In Sustaining Cost (AISC) floor of tangible assets.
The GEDI strips away speculative market noise by compiling three objective, real-world variables into a singular index score:
- War Risk Premium Multiplier: The percentage increase in hull and cargo insurance rates required to clear contested maritime transit zones.
- Transit Volume Suppression: The daily percentage drop in active merchant hull crossings through primary maritime arteries relative to a peaceful seasonal baseline.
- Freight Route Multipliers: The literal distance and fuel penalty incurred when commercial fleets abandon short-haul corridors in favor of defensive detours, such as the long-haul route around the Cape of Good Hope.
24-Month GEDI Trajectory Log
The component logs below outline the historical progression of the GEDI, capturing the transition from baseline shipping conditions into the current structural logistics squeeze:
| Evaluation Window | War Risk Insurance Multiplier | Transit Crossing Volume (Daily Average) | Long-Haul Freight Route Factor | Calculated GEDI Score |
| October 2024 (Baseline) | 1.0× (Standard) | 75 Ships / Day | 1.0 (Direct Route) | 1.00 |
| April 2025 (Initial Friction) | 3.5× | 62 Ships / Day | 1.2 (Partial Detours) | 4.85 |
| October 2025 (Escalation) | 12.0× | 48 Ships / Day | 1.8 (Cape Route Adoption) | 18.40 |
| April 2026 (Blockade) | 22.5× | 38 Ships / Day | 2.4 (Total Sea Avoidance) | 31.10 |
| October 2026 (Current Audit) | 30.0× | 31 Ships / Day | 2.6 (Complete Maritime Reroute) | 42.19 |
The jump to a critical GEDI score of 42.19 provides the direct mechanical explanation for why physical Dated Brent oil remains structurally elevated above normal historical baselines. Crucially, a profound macro validation has emerged within the energy island corridors: while a diplomatic correction has temporarily cooled physical Dated Brent down to $117.00/bbl from its recent extreme spike, standard Brent paper futures have simultaneously climbed to $110.00/bbl.
This narrow $7.00 spread represents a powerful convergence mechanism. The paper derivatives market is finally being forced to capitulate to physical reality; standard paper contracts can no longer ignore the structural weight of the GEDI squeeze and are actively grinding upward to match the real-world overhead of fuel burn, insurance premiums, and extended transit timelines.
This convergence serves as an early-warning feedback loop for the silver model. Higher GEDI scores mean sustained, embedded transport costs that feed directly into national retail diesel averages ($6.53/gallon). Because primary base-metal mining operations rely entirely on diesel-powered heavy machinery and multi-leg freight distribution, a sustained GEDI squeeze mathematically forces primary mining costs higher, capping global supply responses and accelerating the structural drawdown of Western bullion vaults. The overall effect of higher diesel prices on the overall economy only exacerbates the situation.
Section 3: Supply Chain Vault Drains and Exchange Settlement Dynamics
The structural divergence between synthetic paper indexes and physical realities is further confirmed by raw international logistics manifests and exchange clearinghouse volume logs as of late October 2026. While Western digital tickers react to high-frequency algorithmic swings, a historical, ongoing physical migration has completely bypassed traditional futures pricing models.
Official Chinese Customs Authority trade data verifies that a monumental, non-linear physical vacuum has been active throughout 2026 [Chinese Customs Authority]. Led by an extraordinary all-time single-month record of 836 metric tons of physical silver, Chinese physical imports surged an incredible 173% above the 10-year seasonal baseline [Chinese Customs Authority]. This structural siphon has hollowed out available unencumbered floats across Western vaults at a record pace.
Because physical availability has tightened drastically, and active maritime routing faces acute geopolitical friction, sophisticated premium buyers in Eastern hubs have increasingly turned to secure cargo networks. With Chinese domestic physical premiums consistently trading 12% to 17% higher than Western paper spot prices, high-value capital has established a highly lucrative arbitrage corridor. Institutional allocators have systematically bought physical bullion at artificial COMEX/LBMA discounts, utilizing chartered air freight to transport physical bars directly to secure Eastern vaults to capture unsuppressed premiums before the Ministry of Commerce’s two-year strategic export licensing restrictions tighten further through December 31, 2027.
This relentless drainage of the West’s physical float is heading directly into a severe structural bottleneck on the New York COMEX exchange. An audit of the live CME Group volume and open interest logs reveals an intense concentration of paper claims waiting in the upcoming delivery cycles:
The November Notice Period (SIX26): The front-month November contract remains an inactive, quiet cycle, carrying a minor open interest of just 470 active contracts (representing 2.35 million ounces of paper silver). Institutional house desks traditionally utilize these low-volume, quiet windows to systematically clear out short exposures and settle proprietary contracts outside the public eye.
The December Terminal Wall (SIZ26): Positioned immediately behind it sits the true structural delivery trap. The December 2026 contract carries a massive, towering open interest of 83,112 active contracts—representing a staggering 415.5 million ounces of synthetic paper claims sitting on the board.
When these paper metrics are layered against physical constraints, a profound fractional-reserve imbalance emerges. The entire available unencumbered free float across the London LBMA OTC vaults is restricted to approximately 300.7 million ounces, while the COMEX deliverable registered float remains pinned under the 100 million ounce line. In institutional reality, acute delivery imbalances on regulated exchanges are historically resolved via rules-based settlement modifications, cash premiums, or forced liquidation-only mandates rather than a systemic market collapse.
However, this regulatory safety valve introduces a severe operational break for the physical economy. While financialized allocators may accept cash settlements, industrial procurement desks cannot manufacture physical solar infrastructure or high-grade semiconductors out of an exchange check. Consequently, a forced paper settlement mechanism triggers an absolute decoupling, pushing commercial procurement completely outside the exchange environment and driving unsuppressed over-the-counter premiums for physical bullion.
General Discussion & Report Conclusion
The data compiled across this October 19 audit demonstrates that the foundational silver repricing thesis remains mathematically supported, independent of short-term paper derivative fluctuations. The market is functioning under a profound informational lag. Mainstream analysts remain structurally blind to the physical mechanics of the solar procurement floor, embedding a localized 30% solar-segment thrifting projection—which represents a minor 3.5% variance in aggregate global demand—into total industrial collapse models. They continue to treat silver as a standard speculative financial asset, completely ignoring the reality that it is a finite industrial element being systematically drained from a vault system that has lost over 762 million ounces in six years.
The divergence between public institutional projections and physical warehouse positioning indicates that institutional smart money is actively preparing for an eventual structural decoupling [J.P. Morgan]. While macro capital fleeing sovereign debt walls historically favors larger, deep-liquidity asset classes like Gold, Bitcoin, or short-duration high-yield instruments, silver occupies a unique dual-nature position. It captures a portion of defensive monetary flight while concurrently relying on an unyielding, price-inelastic industrial baseline.
When the broader market finally exposes the flawed logic of the institutional demand-destruction narrative—and acknowledges the ongoing air-freight drain to Eastern secure hubs—the underlying structural deficit will become impossible to mask. As the GEDI-driven energy squeeze increases overall structural inflation alongside a permanent upward re-baselining of global extraction costs, the transition out of financialized paper instruments and into unencumbered hard assets will transition from a defensive asset rotation into an absolute physical scramble. Until that inflection point arrives, the fractional paper market will continue to provide a high-value accumulation window for participants positioned to hold physical custody through the impending winter settlement squeeze.