Section I: Summary and Introduction
This analysis is a revision of our Sept 17th article expanding upon initial open-source intelligence tracking (such as reporting by the Hal Turner Radio Show: https://halturnerradioshow.com/index.php/news-selections/national-news/speaker-of-irans-parliament-trolls-federal-reserve-over-interest-rate-hike-iran-is-now-the-entity-setting-us-financial-policy?highlight=WyJnaGFsaWJhZiIsImdoYWxpYmFmJ3MiXQ==
) which first highlighted the broader strategic gravity of Ghalibaf’s post.
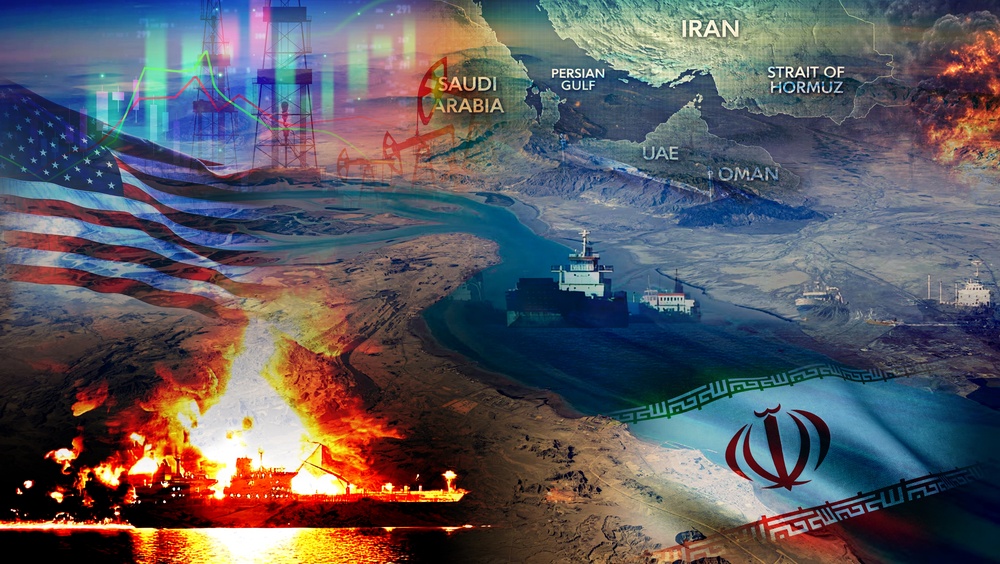
Iranian Parliament Speaker Mohammad Bagher Ghalibaf recently posted a modified “Taylor Rule” formula to social media, appending coefficients for the operational status of the Strait of Hormuz (SOH) and the Bab el-Mandeb (BEM) chokepoints. The standard Taylor Rule is a foundational monetary policy framework designed to act as an objective guideline for central banks, prescribing that interest rates should rise when inflation exceeds target thresholds or when the domestic economy is “overheating.”
The post was very brief and included a modification of the Taylor Rule and what could be interpreted as a challenge:
“Let’s see if a hike could open SOH or produce a single barrel. 🙂 You can’t 25 bp a chokepoint and r* isn’t neutral. It’s SOH risk premium and We set it.”
Many observers gave the post a superficial glance and dismissed it. Too much math apparently, very scary… The somewhat snarky tone of the text itself coupled with the smiley face it included apparently led many of those who did comment on it to dismiss it as a troll or a joke. I am going to come back to this and the implications of this later, aside from stating here that categorizing it as a joke is a serious mistake.
We should now take a look at the actual formula given that its implications are grave: it suggests the Federal Reserve is caught in a structural trap where its only tool to combat supply-driven energy inflation is to enforce severe domestic demand destruction—effectively forcing a recession to lower oil prices.
Section II: The Taylor Rule
As stated above, the standard Taylor Rule is a foundational monetary policy framework designed to act as an objective guideline for central banks, prescribing that interest rates should be increased when inflation exceeds target thresholds or when the domestic economy is overheating.
The variables in the 1993 Taylor Rule formula R=p+r∗+0.5(p−p∗)+0.5y represent the following economic indicators:
- R: The nominal federal funds rate (the target short-term interest rate set by the central bank).
- p: The current rate of inflation (typically measured over the previous four quarters).
- r∗: The equilibrium real federal funds rate, representing the assumed long-run real interest rate consistent with full employment (often assumed to be 2%).
- p∗: The target inflation rate, which is the central bank’s objective for price stability (commonly set at 2%).
- y: The output gap, defined as the percent deviation of real GDP from its potential or trend level.
The coefficients 0.5 indicate that the interest rate adjusts by half a percentage point for every one percentage point deviation in either inflation from its target or output from its potential.
Note that a revision was made in 1999. The Fed doesn’t formally adopt either version as an official policy rule — they use it as a reference tool to sanity-check where rates “should” be. That said, the 1999 version (with a coefficient of 1.0 on the output gap instead of 0.5) is the one that better tracks actual FOMC behavior, and it’s the one more commonly used in FED internal analyses. Ghalibaf used the older version but added a petroleum price inflation component.
The true policy prescription dictated by the formula is currently being artificially masked by massive draw downs of the Strategic Petroleum Reserve (SPR), which keep oil prices temporarily suppressed. However, once this fiscal buffer is exhausted in the coming months, the true structural inflation from the maritime blockades will pass through into headline data. At that point, the Taylor Rule will mathematically demand a massive rate spike, fully exposing the trap: the Fed will be forced to choose between ignoring its own reference tools or raising rates to a level that collapses the domestic economy.
Section III: The Taylor Rule and the FED
Let’s fill in the data. Recall that the equation is:
R=p + r∗ +0.5(p−p∗) +0.5y
Prior to the current conflict, the benchmark federal funds rate sat at a steady target range of 3.50% to 3.75%, anchored by a headline annual inflation rate of 2.68% and a positive real output gap estimated at 2.0%. Plugging these exact pre-war metrics gives us:
R = 2.68 +2.0 +0.5 (2.68 −2.0) +0.5 (2.0) = 𝟔.𝟎𝟐%
Because the economy exhibited strong output momentum and inflation sat slightly above the 2.0% target, the rigid formula demanded a theoretical rate of 6.02%, while real-world policymakers chose to exercise caution to protect financial stability.
That this decision itself calls into question the use of the equation in the first place suggests a whole different discussion, and readers can certainly find that elsewhere on the internet. The fact is, Ghalibaf did use it, and that is what we are discussing here, namely, its relevance implications.
To map out how a cost-push oil crisis impacts this prescription, we evaluate projections across four distinct oil price milestones—moving from this stable pre-war baseline into the current phase where prices are being temporarily anchored by emergency Strategic Petroleum Reserve (SPR) draw downs, and finally looking ahead to the price spikes that occur once that buffer is exhausted. All scenarios hold the output gap constant at +2% to isolate the inflation channel; a simultaneous output contraction (as would be expected under a severe supply disruption) would reduce the implied rate.
| Geopolitical & Oil Price Scenario | Projected Inflation Rate | Taylor 1993 Rule Rate | Taylor 1999 Rule Rate |
| $75.00 Per Barrel (Pre-Disruption Baseline) | 2.68% | 6.02% | 7.02% |
| $93.75 Per Barrel (¼ Distance / Partial Disruption) | 3.15% | 6.72% | 7.72% |
| $112.50 Per Barrel (Midpoint Price Scenario) | 3.62% | 7.43% | 8.43% |
| $150.00 Per Barrel (Postulated Severe Peak) | 4.55% | 8.83% | 9.83% |
| $190.00 Per Barrel (Extreme Structural Upper-Bound) | 5.55% | 10.33% | 11.33% |
Section IV: Methodology & Modeling Frictions
To generate these scenario-based trajectories, we combine traditional central banking heuristics (the Taylor Rule) with forward-looking DSGE-based staff models in which agents (e.g., households, firms) form expectations about future conditions:
The Federal Reserve “Rule of Thumb” baseline pricing mechanism relies on a standard linear heuristic utilized by central bank researchers. It dictates that every $10 increase in the price of crude oil adds approximately 0.25 percentage points to headline annual inflation, assuming a smooth, gradual pass-through of energy costs into consumer goods and services. This linear pass-through assumption (≈0.25 pp per $10) is calibrated to small, transitory shocks in stable regimes. Empirical evidence (Hamilton 2005; Kilian & Vigfusson 2011; CEPR 2026) indicates that pass-through is asymmetric, convex in shock size, and regime-dependent. These properties compound under a large, persistent supply disruption such as a sustained Strait of Hormuz closure, where the linear rule likely underestimates both the magnitude and persistence of the inflationary impulse. However, given that the framework remains in active use by central bank staff and market participants, and that our objective here is to span the range of plausible scenarios rather than identify the most accurate single estimate, we retain it in the table.
The Structural Disruption Framework is arguably superior to the aforementioned methodology. It explains the non-linear upper bounds of the table, such as the $190 extreme spike associated with a 100% total closure of the Strait of Hormuz. Rather than relying on simple linear increments, structural supply models factor in immediate physical and logistical frictions such as sudden spikes in maritime insurance risk premiums, the compounding costs of rerouting shipping fleets around the Cape of Good Hope, and localized refinery bottlenecks. Thus this methodology addresses the blockade induced inflationary spikes that vastly overshoot the linear pass-through estimates described above.
Section V: The Core Policy Dilemma and Domestic Impacts
The projections illustrate the exact systemic risk highlighted by the “Straits Taylor Rule” analysis:
Because the Taylor Rule applies a 1.5× coefficient to the inflation level, supply-side spikes drive proportionally large interest rate prescriptions. Moving from a stable $75 baseline to a severe $150 oil scenario lifts the prescribed 1993 Taylor rate from 6.02% to 8.83%. Furthermore, the Taylor 1999 variant places a full 1.0 multiplier weight on the real output gap. If the crisis escalates to the extreme $190 structural upper bound while trailing economic data still reflects strong pre-war output momentum, the formula demands a staggering 11.33% policy rate.
This highlights the exact tactical leverage Ghalibaf’s post exposed. The mathematical architecture of a central bank’s policy rule blindly demands higher interest rates to crush consumer demand whenever headline prices rise. It should be evident that tightening monetary policy cannot clear a physically blocked shipping lane, lower maritime insurance premiums, or reduce the transit time of a rerouted oil tanker.
A rigorous analysis of the situation exposes how severely constrained the Federal Reserve actually is by its own metrics, methodology, and internal adjustments. This profound divergence calls into question the baseline applicability of these mathematical models, exposing a high degree of subjectivity in real-world policy execution. Because global markets, corporate investments, and individual livelihoods directly rely on these benchmark numbers to make critical long-term financial decisions, such systemic subjectivity is deeply alarming. It suggests that while the public is forced to anchor their financial lives to these rigid metrics, policymakers are fundamentally improvising behind the scenes.
This raises a critical question regarding the structural integrity and seriousness of central bank modeling: If the foundational equations are casually overridden whenever they demand uncomfortable adjustments, the entire analytical framework begins to resemble an exercise in narrative management rather than objective science. Rather than operating on a stable, resilient foundation, the global monetary system is being held together by temporary, ad-hoc interventions, leaving the domestic economy structurally exposed to incoming supply-side shocks.
With the national debt exceeding $40 trillion, sustaining actual interest rates anywhere near these structurally prescribed levels would force an unprecedented fiscal crisis, driving government debt-servicing costs to catastrophic levels and freezing commercial credit markets. The market’s rational defense mechanism against this vulnerability is a structural flight from sovereign debt obligations, as capital realizes the central bank cannot use demand-side tools to fix the physical supply-side situation, i.e. the blockade.
Section VI: Of Trolls and Leviathan – Narrative and Deception
While mainstream commentators uniformly dismiss Ghalibaf’s modified formula as mere internet satire, the “Troll” label serves a structural function: It allows market participants and the public to disregard a brutal macroeconomic reality. If geopolitical conflicts trigger a sustained closure of these maritime chokepoints, the resulting cost-push energy shock creates severe supply-side inflation that traditional central banking tools are fundamentally unequipped to resolve. Serious examination of the math – of the Taylor Rule – exposes the implications of the Iran/US/Israel War. A fundamentally localized physical blockade is forcing a highly destructive trade-off: the Federal Reserve’s mathematical mandates compel it to hike interest rates aggressively to combat escalating energy prices, even as the real economy faces a supply-induced contraction. Far from a simple joke, Ghalibaf’s formula acts as a conceptual framework for asymmetric economic warfare—mapping out a structural economic trap that leverages the Fed’s own policy rules against the domestic financial system, or minimally, the narrative about how things are supposed to work.
By classifying the ‘Straits Taylor Rule’ as a harmless joke, the financial establishment ensures that the underlying mathematical trap is never treated as a legitimate, actionable security threat. Ultimately, this uniform dismissal serves as a vital defense mechanism for the modern monetary Leviathan. The state’s monopoly on authority depends, among other things, on the comforting illusion that its central banks possess total administrative control over the macroeconomic architecture. To admit that a localized physical blockade can completely invalidate the Federal Reserve’s policy levers would expose the profound helplessness of the state. Therefore, the Leviathan’s gatekeepers must aggressively reduce any precise calculation of its structural vulnerabilities to mere internet theater.
In the 72 hours following the post, every major outlet covering it framed it as a joke rather than a threat, demonstrating this systemic blind spot in real-time:
Al Jazeera News dismissed it as a “spectacular bit of agitprop” from a country that has “demonstrated an impressive ability to needle its US opponent”.
India Today Business and NDTV Profit labeled the equation “satirical” and explicitly stated it “should not be interpreted literally” as Iran determining Fed decisions.
IG Group Chief Market Analyst Chris Beauchamp called it “political theater”.
Cedar News Reports noted that while the math is “loaded with a wartime message,” the remarks were merely a “political and economic argument” rather than a formal proposal.
Again, and put a bit differently, uniform dismissal across mainstream media and institutional analysis serves a psychological and structural function. It allows disregard of the data and mechanics, per se, thus allowing the public to maintain the comforting illusion that central banks (and by extension, the Administration) possess control over the macroeconomic situation. The institutional blind spot is amplified by structural tendencies within automated risk assessment models and human commentators alike. Standard financial risk frameworks are fundamentally engineered to preserve a “stable narrative,” routinely filtering out extreme tail-risk scenarios involving systemic currency degradation or sovereign fiscal insolvency as “unverified opinions” rather than real-time market signals. Incidentally, the Buzzocles Report has addressed this before.
Section VII: Discussion
In the context of asymmetric conflict, treating an adversary’s precise calculation of your monetary system’s structural flaws as a mere internet meme ensures total strategic blindness when those physical vulnerabilities are ultimately exploited. Ghalibaf’s modification of the equation constitutes a mathematical example of a small, asymmetric move (closing a strait) triggering a massive, systemic collapse. The “joke” aspect is the most dangerous part of the situation. If the world treats it as a joke one way or another, it will be blindsided when the math plays out. The Iranians are playing a game of asymmetric economic warfare. They are excellent strategists and adept at long term thinking. But there is more here than may meet the eye.
While conventional financial commentators remained hyper-focused on the superficial tone of the social media text, rigorous tracking of the underlying macroeconomic variables reveals that the core thesis is correct: A severe petroleum chokepoint closure creates an unavoidable inflationary penalty that the Federal Reserve cannot mathematically neutralize or ignore.
Raising the benchmark interest rate, a demand-side tool, does nothing to open the shipping lanes, rather, it will crush the US economy. For this reason, it will almost certainly not be imposed. Read carefully: the FED cannot and will not raise rates in accordance with the “rule.” The FED was not doing so prior to the beginning of the War (e.g., ~3.5% vs ~6%) but if the basic relationship conveyed by the Taylor Rule is valid, even as a rough guide, and if the projections for petroleum price inflation are anywhere near correct, what will be the solution?
It appears likely that there is none. Or more accurately, there will be none unless the War ends very soon. Even then there will be dramatic impacts. Absent this, inflation will increase, probably once the drawdown of the Strategic Petroleum Reserve (the only thing that has kept the whole situation from falling apart in the first place) becomes impossible to maintain. And that is the good news. All things being equal, i.e., if the trends continue, the US will suffer a dramatic re-experience of the stagflation of the 1970s.
The bad news is in the conclusion below.
Conclusion
The obvious conclusions are:
- It is a mistake to regard the Ghalibaf post as a joke. Yes, the man may have a sense of humor, and there was probably a hint of satire in it –especially given the inclusion of the smiley face and the fact that he apparently just tossed in a random dramatic rate number.
- Our investigation of the Taylor Rule and the current situation reveals that the US is trapped. It really is that basic. Put another way, Ghalibaf is right. Credit where credit is due.
The Rational Actor Model of decision making is broadly applicable to many situations in life. Broadly stated, it maintains that when observed behavior appears to be irrational, the problem is not necessarily that it is. Yes, sometimes the actor is behaving irrationally. But sometimes, the apparent irrationality stems not from the actor itself, but rather from misunderstanding, or incomplete understanding, of the motivations of the actor, the data itself, and/or the mechanisms or equations describing the situation itself.
Applied here, and given the apparent irrationality of the US continuing to escalate by continuing military strikes and maintaining an intractable diplomatic position, one has to wonder what the motivations actually are. While one might hope that whoever is actually in charge really is irrational and/or incompetent, the bad news is that they may not be.